


EXCLUSIVE| MMDR Theater in Odisha Assembly: BJD's Cash Race and Congress U-Turn Not Only Betrays Rajiv-Manmohan Legacy but Leave the Common Voter Biggest Loser
Key Points
Assembly Disruption: The Odisha Assembly witnessed consecutive disruptions and adjournments by Congress and BJD members protesting the MMDR Amendment Act and Section 9D.
The U-Turn: When Prime Ministers Rajiv Gandhi and Manmohan Singh firmly resisted separate state mineral cesses to protect the national economy, an out-of-power Congress did a complete U-turn
Economic Downstream Impact: Upstream mineral cesses ripple across the economy, eventually impacting input costs for core industries, infrastructure, and everyday consumers.
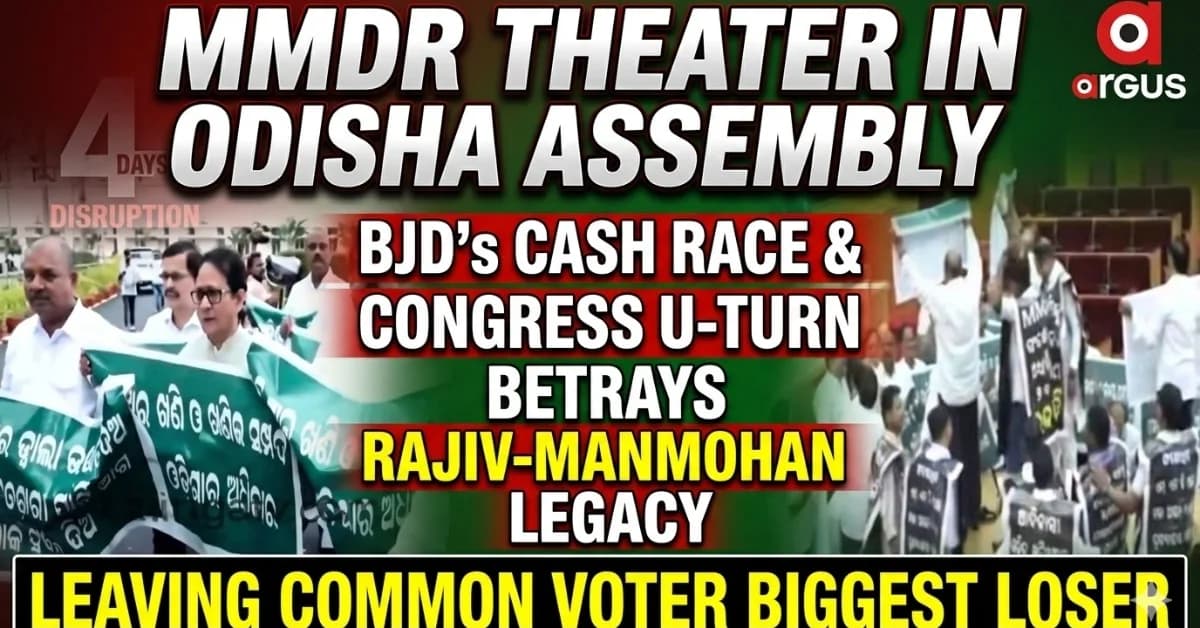
Bhubaneswar: The Odisha Assembly assembled on Friday. The Congress and BJD members rose. Slogans followed. Placards went up. Members entered the Well. The Question Hour barely got going before the House was adjourned.
And that was the fourth consecutive day of disruption over the Mines and Minerals (Development and Regulation) Amendment Act, 2026.
On Thursday, the pattern was much the same. Congress, BJD members entered the Well with placards and slogans; some stood on reporters' tables, while Congress members wore black gowns written over with slogans agaist MMDR. The Deputy Speaker eventually adjourned the House till 4 pm and later till the next sitting.
The political theatre has become unmistakable: protest inside the Well, slogans before the Chair, placards and black gowns for the cameras and demands for withdrawal of the law before discussion.

📱 Get Argus News App
✨There is an almost ironic parallel outside the Assembly. When the Deep Depression is washing away river embankments and raising flood fears across Odisha, a political Deep Depression is washing away the Assembly's scheduled business.
Four days. Little substantive debate. No sustained argument-counter-argument on the floor. Instead, direct action: protest, disruption and adjournment.
But beneath the noise lies a question that ordinary people deserve to have answered:
Is Odisha actually losing ₹1 lakh crore of money it was already earning – or is the figure referring to revenue the State expected to collect in the future after the Supreme Court's 2024 verdict?
That distinction changes the entire story.
So, amid the weather-induced Deep Depression and the political Deep Depression inside the Assembly, it is time to clear the haze – one fact at a time.
The first fact: Odisha's mining revenue did not begin with the 2026 amendment
Look at Odisha's mining earnings over time.
Before the present controversy, the State was already earning thousands of crores annually from royalties and other mining-related streams. After the 2015 reforms and auction regime, the scale changed dramatically.
The supplied revenue series shows the transition clearly.
Odisha's mining revenue before DMF: 2010-11 to 2014-15
|
Financial year |
Core mining revenue* |
|---|---|
|
2010-11 |
₹3,330.46 crore |
|
2011-12 |
₹4,586.64 crore |
|
2012-13 |
₹5,679.35 crore |
|
2013-14 |
₹5,519.57 crore |
|
2014-15 |
₹5,335.05 crore |
The core mining revenue then was royalty + auction premium. DMF was not yet part of the revenue series during these years.
This is important because it establishes the baseline.
Odisha was not a State with no mining income waiting for the 2024 Supreme Court judgment to unlock it.
It was already earning substantial mineral revenue.
Then came the post-2015 transformation
|
Financial year |
Core mining revenue |
DMF collection |
Combined figure thereafter |
|---|---|---|---|
|
2015-16 |
~₹5,800 cr |
Transition year |
~₹5,800 cr |
|
2016-17 |
₹5,134.90 cr |
₹2,193.63 cr |
₹7,328.53 cr |
|
2017-18 |
~₹6,131 cr |
~₹2,000 cr |
~₹8,131 cr |
|
2018-19 |
~₹10,479 cr |
~₹2,500 cr |
~₹12,979 cr |
|
2019-20 |
~₹11,020 cr |
~₹2,800 cr |
~₹13,820 cr |
|
2020-21 |
~₹13,918 cr |
~₹3,200 cr |
~₹17,118 cr |
|
2021-22 |
₹44,500 cr |
₹5,359.12 cr |
₹49,859.12 cr |
|
2022-23 |
~₹38,000 cr |
~₹4,500 cr |
~₹42,500 cr |
|
2023-24 |
~₹44,000 cr |
~₹4,600 cr |
~₹48,600 cr |
|
2024-25 |
~₹45,500 cr |
~₹4,300 cr |
~₹49,800 cr |
|
2025-26 |
₹46,710.57 cr |
₹4,416.53 cr |
₹51,127.10 cr |
The latest full-year figure in the supplied data is 2025-26; FY 2026-27 is not a completed financial year yet.
The point is simple.
Odisha's existing mining revenue stream has not disappeared because of the 2026 amendment.
Indeed, the Union government says around 90% of mining-sector revenue continues to accrue to the States and that the amendment does not take away existing State-collected taxes.
What is Section 9D?
Since this has been the heart of the controversy, here is the explaination.
The 2026 amendment inserted Section 9D into the MMDR Act.
In simple language, the provision prevents a State from independently imposing a fresh tax, cess or other levy on mineral rights or mineral-bearing land unless it complies with conditions or restrictions prescribed by the Centre. The provision also deals with unpaid retrospective levies: amounts that had not been paid or collected before the amendment are treated as invalid, while amounts already recovered are not to be refunded.
So, what remains?
Royalty remains. Auction premiums remain. DMF collections remain.
What changes is the State's ability to create an additional layer of mineral taxation outside the centrally prescribed framework.
That is the crucial distinction.
The above distrinction and analysis puts the existing revenue position bluntly: the State's historical and current mining earnings are not being deducted from its account by Section 9D. What is affected is the opportunity to collect additional retrospective and future State-level levies.
And that brings us to the tom-tomming of headline numbers: Rs1 lakh crore.
The legal story did not begin in 2026 — it goes back to 1989
To understand today's Assembly confrontation, one has to go back nearly four decades.
In India Cement Ltd. v. State of Tamil Nadu, decided in 1989, the Supreme Court held that royalty was a tax and that a State could not impose a cess on royalty in the manner challenged in that case. The Court relied heavily on the central MMDR framework and Entry 54 of the Union List.
That became the central legal reference point for decades.
States did not simply surrender.
Mineral-rich States continued to enact or defend different forms of levies, while mining companies challenged them in court. That produced another major constitutional battle in State of West Bengal v. Kesoram Industries, decided in 2004.
Here the legal picture became more complicated: the Supreme Court held in that case that a State levy on land could be constitutionally valid in the circumstances before it. The judgment itself discussed Entries 49 and 50 of the State List and the relationship with Parliament's powers under Entry 54.
The disagreement did not end there.
In 2011, in the Mineral Area Development Authority v. Steel Authority of India litigation, the Supreme Court referred the fundamental questions to a nine-judge Constitution Bench. Among the questions was whether royalty was a tax and what limitations Parliament's MMDR legislation imposed on the States' power to tax mineral rights.
The dispute therefore travelled from 1989 → 2004 → 2011 → 2024 → 2026.
It is not a dispute born inside the Odisha Assembly this week.
Congress, UPA and the Centre: what did the courtroom record show?
This is where the political argument becomes particularly interesting.
The analysis points to a broad institutional continuity in the Union's approach during the UPA years, including its insistence on the importance of Parliament's role under Entry 54 and concern over separate State mineral levies. A glance shows crystal clearly what had been the UPA-era legal and policy position around the Kesoram and MADA/SAIL litigation.
The cleaner comparison is therefore this:
|
Issue |
Rajiv Gandhi/UPA-era position reflected in the record |
Modi government / 2024-26 position |
|---|---|---|
|
Central role under Entry 54 |
Defended the Union's role in mineral regulation and national economic uniformity in 1989 |
Continued to defend the Union's role |
|
State mineral levies |
Union legal position generally resisted uncoordinated additional mineral taxation by States right from 1989, 2004 to 2011 in SC |
Opposed unrestricted additional State levies |
|
2011 MADA-SAIL reference |
Dispute was referred to nine-judge Bench |
Nine-judge Bench finally decided the issue in 2024 |
|
July 2024 judgment |
— |
Supreme Court held royalty is not a tax and recognised State taxing powers over mineral rights, subject to constitutional limits |
|
After 2024 judgment |
— |
Centre pursued review/curative legal routes and then enacted 2026 amendment |
|
2026 Section 9D |
— |
Fresh State levies restricted to Centre-prescribed conditions; uncollected retrospective levies invalidated |
The BIG SC Verdict that has become the Congress and BJD's theatre of disruption in State Assembly Has this Mega Caveat:
The 9-judge bench explicitly noted that “under Entry 54 of the Union List (List I), the Parliament has the ultimate sovereign power to limit, cap, or completely prohibit states from taxing mineral rights if it dictates that doing so is in the "public interest" or necessary for national industrial development.”
Why did governments at the Centre repeatedly worry about State mineral taxes?
There is a basic economic reason behind the Union's recurring position.
India's steel, cement, electricity, aluminium, infrastructure and several other industries depend heavily on minerals. If every mineral-producing State were free to impose a separate layer of taxation on the same mineral base, the final cost could vary sharply from State to State.
That is precisely the argument the Union has advanced in the present controversy: tax uncertainty and overlapping levies can affect investment, production costs and downstream industries. The Union's 2026 explanation says the amendment is intended to create a more predictable fiscal framework and avoid cascading costs.
There is also a constitutional dimension.
The Union's position has repeatedly rested on Entry 54 of List I, under which Parliament can legislate regarding regulation and development of mines and minerals in the public interest.
So what does the headline ₹1 lakh crore really mean?
Strip away the Assembly slogans and the answer becomes relatively simple.
It does not mean Odisha's present mining revenue will suddenly fall by Rs1 lakh crore.
The State will continue to receive its statutory royalty and other existing mining-related revenue streams. DMF collections also continue under the amended framework. The Centre says approximately 90% of mining-sector revenue continues to accrue to States.
The large number principally refers to the retrospective revenue opportunity that emerged after the Supreme Court's 2024 ruling and the subsequent permission to recover certain past dues from April 1, 2005.
That was a potentially enormous future receipt for mineral-rich States.
Section 9D has now shut that door for unpaid/uncollected levies.
So the political argument is about what Odisha could have collected, not about what Odisha had already collected and has now lost.
That is a much more precise way of explaining the ₹1 lakh crore headline.
The Clincher: Additional Mineral Tax Demand and the Common Man — The Real Economics
This is where the MMDR controversy moves beyond political slogans and enters the real economics of the common man.
The central question is not simply whether Odisha, Jharkhand or any other mineral-rich State should have greater fiscal autonomy. The harder question is: who ultimately pays when another layer of tax is added to the mineral economy?
A State cess may begin as a demand for additional revenue from mining companies. But minerals do not remain inside a mine. Iron ore goes into steel; coal goes into power; steel and power go into construction, transport, manufacturing and almost every part of the economy.
The additional cost can therefore travel down the entire economic chain.
From Mine to Market: Where the Cost Can Travel
The
first hit is at the mine.
An
additional State-level cess or surcharge raises the effective cost of
extracting or moving the mineral. For a mining company operating on
tight margins, the additional levy can affect the economics of
production, investment and expansion.
The
second hit is industry.
Iron
ore is not the final product. Coal is not the final product. They are
inputs into steel, electricity, construction and manufacturing. If
the cost of those inputs rises, downstream industries have to absorb,
pass on or otherwise manage that additional cost.
The
third hit is the consumer.
When
higher input costs move through steel, cement, electricity, transport
and construction, they can eventually appear in the prices paid by
households. The transmission is not always one-to-one – companies
can absorb part of the increase, improve efficiency or source
alternatives – but the economic chain is clear: a
tax imposed upstream can create a cost downstream.
The Mineral Cess Crisis: The ₹1 Lakh Crore Question
This is precisely why the retrospective mineral-tax issue became so large.
After the Supreme Court's 2024 ruling recognised the States' power to tax mineral rights, the possibility emerged of recovering large amounts of previously unpaid levies. The retrospective claims across mineral-producing States were estimated in very large numbers.
For Odisha, the political headline has centred around Rs1 lakh crore and more.
Structural Impact: From Mineral Tax to the Common Man
|
Economic Layer |
Additional Levy / Cost Trigger |
Impact on Mining & Industry |
Possible Impact on Common Man |
|---|---|---|---|
|
Raw Resource Extraction |
Additional mineral cesses, taxes or mineral-bearing land levies |
Raises the effective cost of domestic mineral extraction |
Can increase the cost base of mineral-dependent products |
|
Primary Production |
Mineral levies, transit charges and related costs |
Raises the input cost for steel, power and other mineral-dependent industries |
Can feed into construction, infrastructure and utility costs |
|
Industrial Employment |
Higher cumulative cost of mineral production |
May affect the economics of marginal mines, new projects and expansion decisions |
Slower investment can affect employment and incomes in mining-dependent regions |
|
Transport & Logistics |
Higher fuel and mineral-linked transportation costs |
Raises the cost of moving raw materials and finished goods |
Freight costs can feed into the prices of everyday goods |
|
Retail Consumer Market |
Cumulative upstream cost increases |
Businesses decide how much of the additional cost to absorb or pass on |
Households ultimately face the possibility of higher prices or lower disposable income |
The Bottom Line
This is why the MMDR debate cannot be reduced to “State revenue versus Centre revenue.”
There are actually three layers of economics at work:
What
the State gains.
What industry pays.
What the consumer
ultimately bears.
For mineral-rich States, an additional cess can mean additional fiscal resources for development. For the Centre, limiting overlapping mineral taxation can mean greater predictability in the national industrial economy. For industry, the issue is the cost of the raw material. And for the common man, the question is what portion of that additional cost eventually reaches his electricity bill, house construction, transport expenses or household budget.
That is the real MMDR argument beneath the Assembly drama.
The
political fight may be over optics to cook anti-incumbency and gain
votes. But the economic question is: who finally pays it? The Voters!
Also Read: Analysis| Opposition Optics On Playing To Gallery To Cook Anti-Incumbency After Honeymoon Period, Matured BJP Plays Counter-Optics To Foil The Cook
Related Topics
Explore more stories